Members’ club & hotel · Jávea · since 1967
casa
Tosalet
Business Plan 2026–2034
€4.7M investment opportunityWithin a €5.6M equity round
Target close 30 October 2026 · Confidential — draft for discussion
01 The asset
A historic setting for a new private members’ club
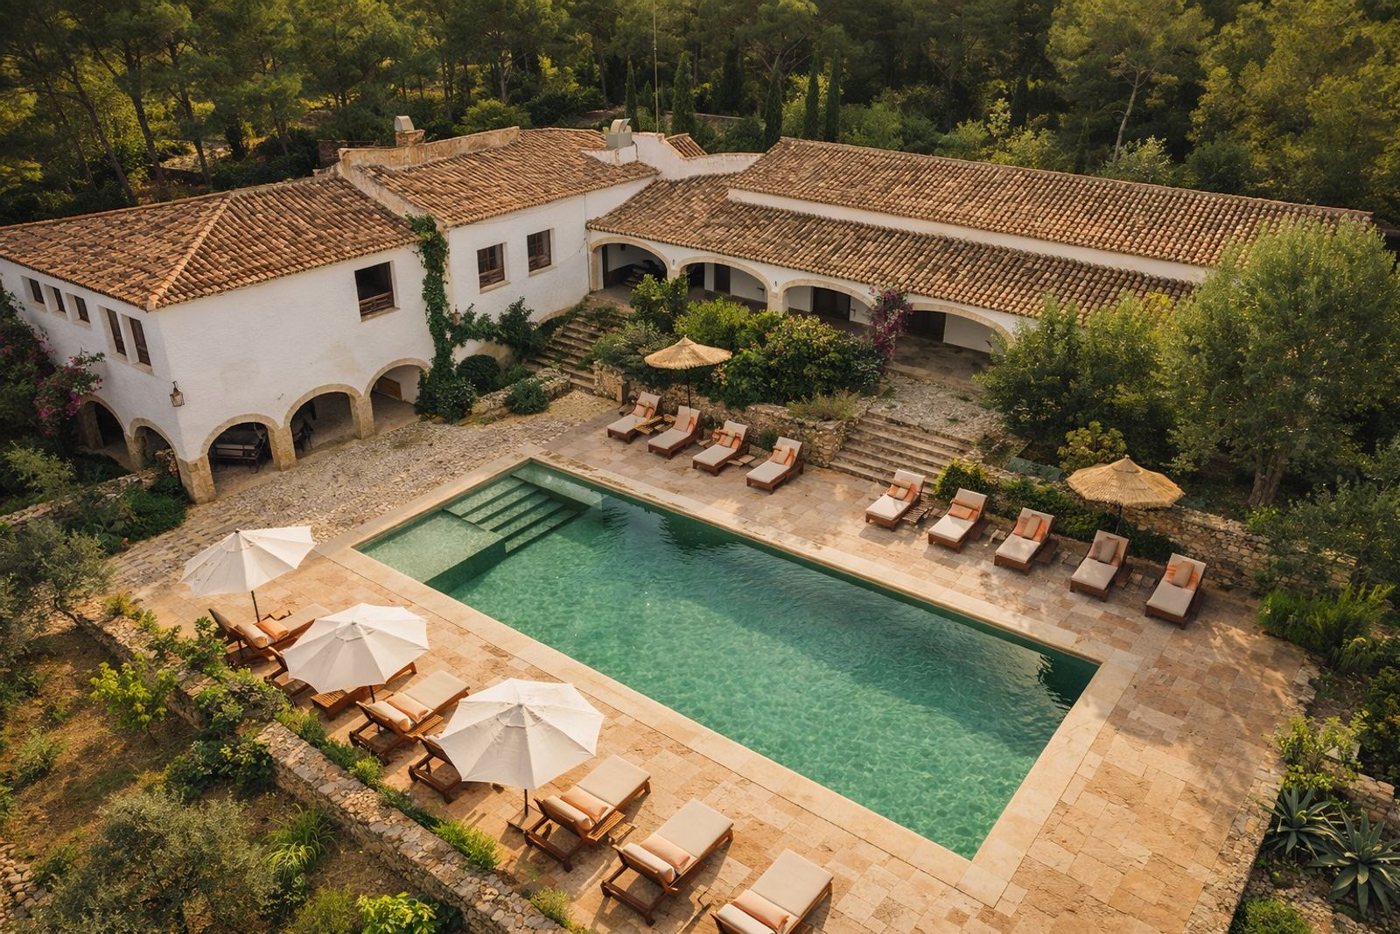
Four adjoining plots above the bay of Jávea, in use as a club since 1967. The property was acquired outright on 8 May 2026, free of charges and without a mortgage, and is to be restored as a private members’ club with 52 keys alongside it.
The setting is long established; the business presented here is new.
↗Partners report · May–August 2026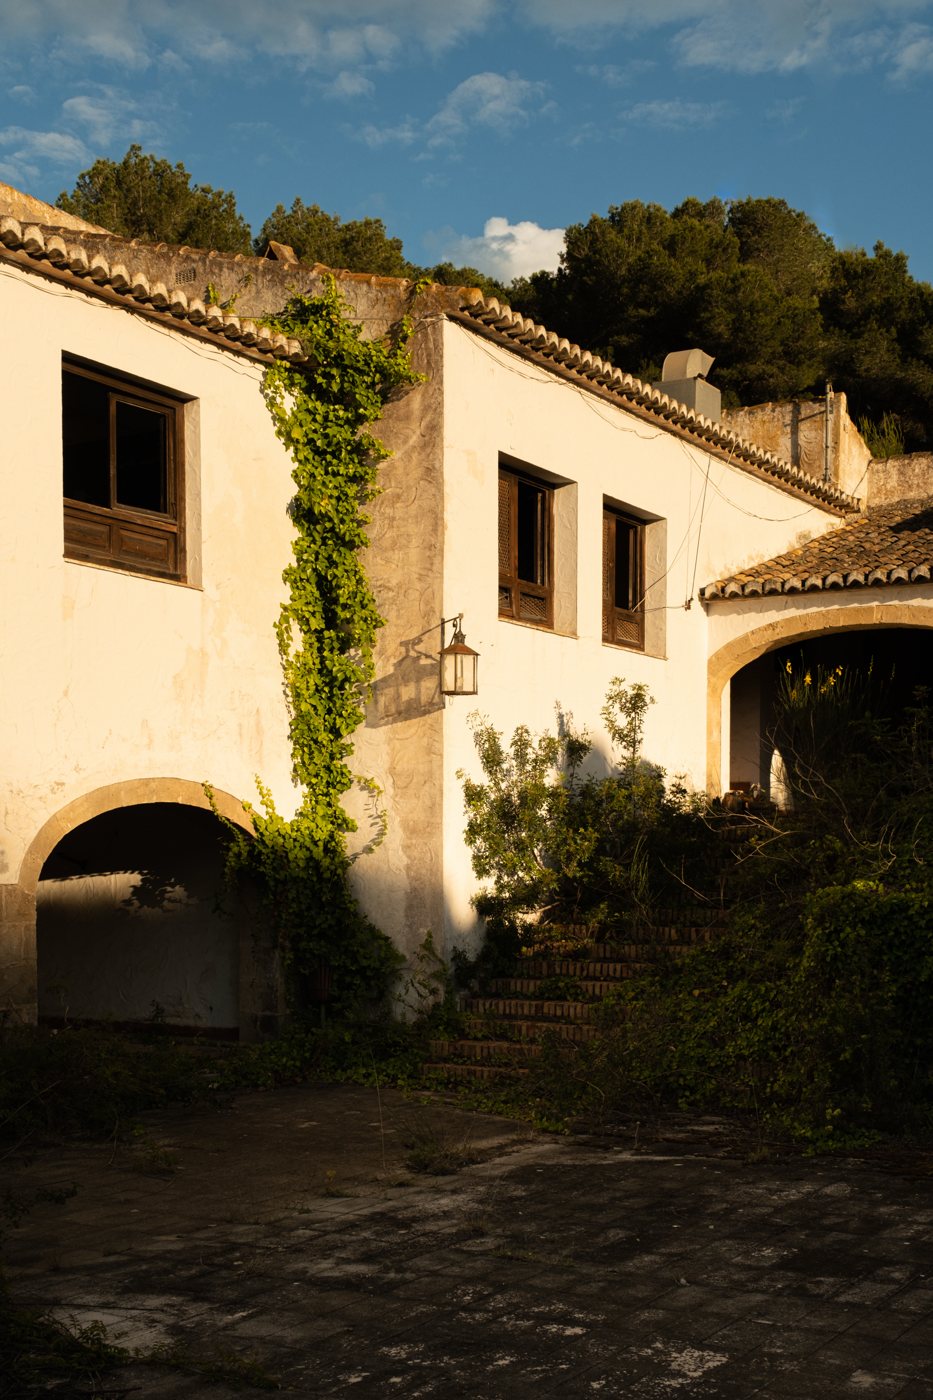
Areas, licence status and unit count as reported in the project base.
02 The product
What a membership buys
One family membership for two adults and their children. A one-off joining fee, then €5,000 a year.
Included in the dues
- Casa Tosalet — its common rooms and the library
- The pools, the gardens and the sports areas
- Access to the spa and the Roman baths
Charged separately
- The table — lunch, dinner and the bar
- Rooms for members and their guests
- Spa treatments, training and private events
03 The structure
One integrated project. Two clearly defined companies.
Operating company — the OpCo
Tosalet Health Club, S.L.
Operates the members’ club and accommodation and manages memberships. The equity round is subscribed here, and this company funds its equity contribution to the property company.
THC shareholders — pro forma after the round
Property company — the PropCo
Owns the land and the building
Carries the development loan and leases the asset to the operating company. Structure proposed, not yet formalised.
Ownership of the property company
€6.50M into the property company only. The fund is not a shareholder of Tosalet Health Club. An 8% return is referenced in the plan as a pending term, not as an agreed coupon, IRR or cap.
Founders: Jessica Bataille and Jean Clauteaux. Existing partners: M. Vergara, F. Díaz Requena, F. Bestebreurtje.
04 Operating assumptions
Membership and hospitality
Four cohorts and a hotel ramp. Modelling assumptions, not commitments.
Joining fees — price-to-model reconciliation pending
| Cohort | Families | Price list VAT incl., as supplied | Model inputs tax basis TBC |
|---|---|---|---|
| 2026 | 100 | €30,000 | €25,000 |
| 2027 | 100 | €35,000 | €25,000 |
| 2028 | 200 | €40,000 | €35,000 |
| 2029 | 100 | €60,000 | €50,000 |
| Total | 500 | €20.50M | €17.00M |
← Swipe to see the columns
Hotel — 52 keys, occupancy
ADR €289 in 2029, indexed 5% a year. The annual dues are €5,000, indexed 2%. The model runs 2029 as a full year from a January opening; a later opening would reduce it. The full 500-family fee base arrives once every cohort has joined.
€20.50M, €17.00M and €15.30M are different measures. The 2029 cohort is collected around opening.
05 Demand
Deposits, lender-linked families and candidates
Position at the September 2026 cut of the membership register. The plan assumes 100 sales in 2026.
Reported figures at September 2026. Categories may overlap and must not be added: the 28 partner families are counted within the 155 names. Loans and deposits are not equivalent to signed membership sales. No paid-in totals or conversion rates are reported.
Source: partners report, May–August 2026.
06 Funding
Sources, uses and commitments
Planned funding and uses, with the reported status of each source.
Planned sources
Planned uses
Lines display rounded and total €32,350,000 exactly. Bank debt is 34% of planned cost.
07 The numbers
Operating outlook, 2029–2034
Projections on the master model of 22 September 2026, built on a January 2029 opening. Joining fees are presented separately from recurring operating revenue; their accounting treatment remains subject to validation.
| € millions | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 |
|---|---|---|---|---|---|---|
| Revenue — club and accommodation | 8.24 | 10.08 | 11.28 | 12.10 | 12.47 | 12.85 |
| of which recurring annual dues | 2.25 | 2.55 | 2.60 | 2.65 | 2.71 | 2.76 |
| OpCo EBITDA after rent to PropCo | 0.53 | 1.55 | 2.22 | 2.62 | 2.72 | 2.83 |
| Consolidated EBITDA | 1.89 | 2.71 | 3.32 | 3.70 | 3.83 | 3.96 |
| EBITDA margin | 23% | 27% | 29% | 31% | 31% | 31% |
← Swipe to see every year
Source: master model of 22 September 2026, which sets club overhead and corrects the room-cost treatment.
08 Liquidity
Cash through development and opening
Consolidated year-end balances, in millions of euro. Annual closes only: a year-end low does not evidence intra-year solvency.
← Swipe across the years
Year-end balances. OpCo and PropCo are added; transfers between them are not documented.
09 Risk
The four things that move this plan
Each one with the mitigation in place and the condition that remains open.
Risk 01
Construction cost
The largest single line at €20.27M, and measurement is not final.
Mitigation in place. A 15% contingency on the measured works, not on the total budget; three contractors priced the same drawings.
Remaining condition. No contract is signed.
Risk 02
Membership pace
The club funds its own construction, so slower sales delay the works.
Mitigation in place. 14 paid deposits reported at September 2026 and a price that rises with each cohort.
Remaining condition. A lower-volume case is being modelled. A price rise does not by itself cover slower take-up.
Risk 03
Opening date
The model assumes a January 2029 opening. Licences or works running long would push it and reduce the first year.
Mitigation in place. A budgeted reserve, and a modelled year-end low of €1.08M in 2028 that stays positive.
Remaining condition. No licence is granted yet, and an April opening has been discussed operationally.
Risk 04
Financing close
Neither the bank facility nor the European fund is agreed in definitive form.
Mitigation in place. Site visits by two senior banks in September 2026, and the land already paid for.
Remaining condition. Definitive agreements. Term sheet, signed document and final agreement are different states.
Bank and fund financing remain subject to definitive agreements. Operating projections remain under review.
10 The round
Your €4.7M investment
€4.7M for approximately 29.75% of Tosalet Health Club — the whole of the round that remains available, assuming completion of the €5.6M round at a €10.2M pre-money valuation.
€0.90M of the €5.60M round is already committed by investors in our network; the remaining €4.70M is available in full or in part. At the 64.6% THC stake in PropCo, a €4.70M holding also carries 19.23% of the property indirectly. Pro forma and conditional on the full €5.6M closing at the same price per share, with no further dilution. Governance, reporting and exit rights to be agreed in the shareholders’ agreement.
11 Returns
What the model returns on €4.7M
A 29.75% holding in the operating company, entered in 2026, valued at each year of the plan.
Exit year · master model of 22 September 2026
| Exit year | OpCo equity value | Your proceeds | MoIC | IRR |
|---|---|---|---|---|
| 2029 | €8.75M | €2.60M | 0.55× | −17.9% |
| 2030 | €22.16M | €6.59M | 1.40× | 8.8% |
| 2031 | €31.96M | €9.51M | 2.02× | 15.1% |
| 2032 | €38.67M | €11.51M | 2.45× | 16.1% |
| 2033 | €42.02M | €12.50M | 2.66× | 15.0% |
| 2034 | €45.51M | €13.54M | 2.88× | 14.1% |
← Swipe to see MoIC and IRR
How the value is built
Operating-company EBITDA in the exit year
Valued at 12× — the multiple carried in the model
Plus the net cash held at that year end
× 29.75%, the holding a €4.7M ticket buys
IRR compounds from 2026, the year of entry, on one subscription and one exit.
These are the model’s own outputs, unadjusted. Two things to hold in mind. The exit year is a modelling horizon, not a committed exit, and any exit right of the European fund follows its final terms. And these figures value the operating company alone: the 19.23% of the property that comes with the holding sits inside it at book value, not at the property’s own exit yield.
Projections on the master model of 22 September 2026. No return is promised or guaranteed.
Casa Tosalet
Everything on this page, in two documents.
The Business Plan as a PDF, and the financial model behind every figure here as an Excel workbook. Both open from the buttons below.
Jessica Bataille · Jean Clauteaux — Tosalet Health Club, S.L. · NIF B-09.805.904 · Jávea, Alicante
Confidential. Projections on the master model of 22 September 2026, subject to reconciliation and to definitive agreements. Nothing on this page is an offer or a promise of return.